Your Income, Engineered

A comfortable retirement begins with a tailored financial blueprint.

Retirement income planning for people who value straight, practical advice and a plan engineered from first principles.

“You’re not hiring us to pick stocks. You’re hiring us to be accountable for the outcome of your financial life.”

Applied Wealth Management is an independent registered investment advisor serving clients nationwide. We coordinate retirement income, investments, insurance, and estate planning under one standard of care, through The Vantage Formula.

The Vantage Formula

On the ground, every account lives in isolation. Our proprietary process moves you to the vantage point, where every decision is visible at once. Learn more

  1. Discovery

    We listen first. Your income, goals, family, and timeline all come before any advice.

  2. Analysis

    An honest assessment of your investments, taxes, insurance, and estate readiness.

  3. Engineering

    A written financial plan and action checklist, coordinated with your CPA and attorney.

  4. Stewardship

    Quarterly reviews and ongoing coordination, so nothing falls through the cracks.

The team behind your plan.

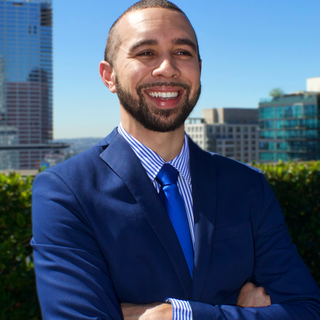
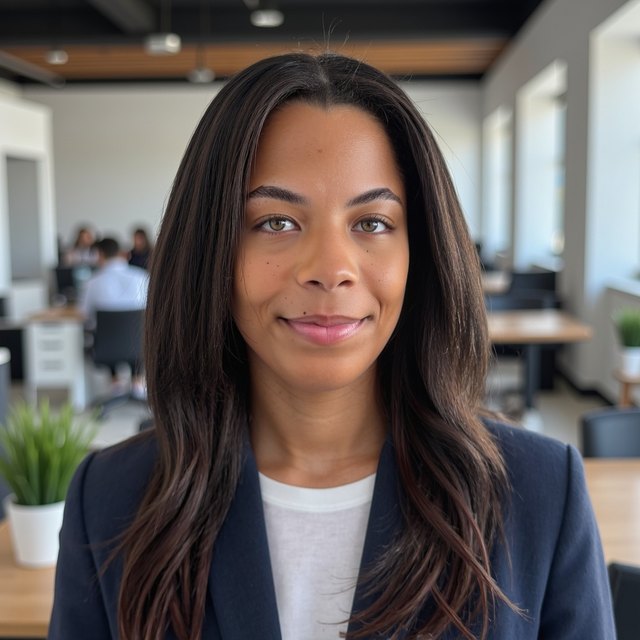
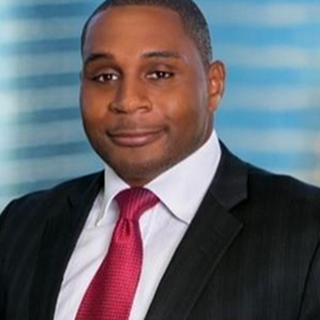
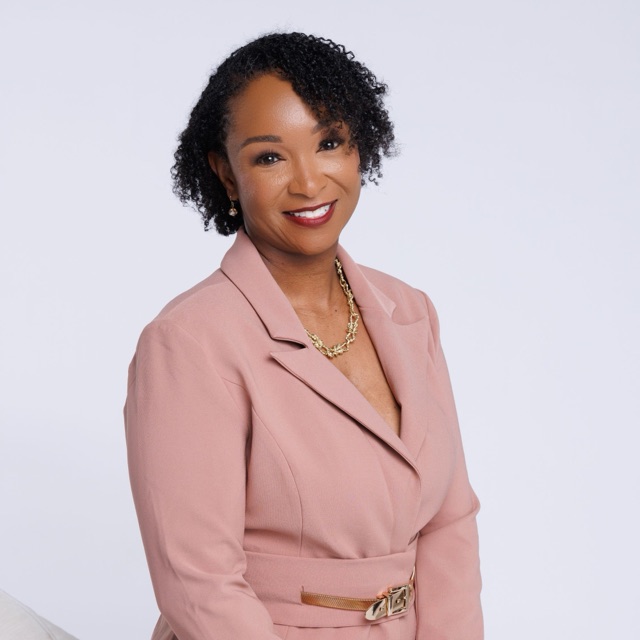
Meet our coordinated team. Each advisor specializes in a different type of client, so whatever your background, you’ll work with someone who knows it well. Open any profile to read the full bio and get in touch.
Common questions and answers

The truth is more useful than the comfortable version of it. If a question here isn’t covered, ask it in your first conversation.

Often yes, but the honest answer depends on how much you spend, not just how much you have saved. Retiring at 60 also means covering five years before Medicare and up to a decade before Social Security, so those early years carry the most risk. We model your real spending against your accounts and show you the age where the numbers hold up. If 60 works, we prove it. If it does not, we show you exactly what would change it.

This is the question retirement really comes down to, and the answer moves as the markets and your life do. Old rules of thumb like the 4 percent rule are a starting point, not an answer, because they ignore your tax picture and the way real spending rises and falls over the years. We set a number you can rely on and revisit it, so a good market lets you spend more and a bad one does not turn into a crisis. The goal is a paycheck you trust, not a budget you dread.

There is no single right age, but for many people waiting past 62 is one of the most valuable moves available, because the benefit grows about 8 percent for every year you delay up to 70. The right claiming age still depends on your health, whether you are still working, your other income, and your spouse’s benefit. We run your actual numbers instead of the rule of thumb, and we coordinate the timing with your withdrawals so you are not overpaying tax in the years you wait.

A Roth conversion moves money from a traditional IRA into a Roth. You pay tax on it now, and everything after that grows and comes out tax-free. Done well, it fills up the lower tax brackets in your early retirement years, before Social Security and required minimum distributions push you higher. The savings can reach six figures over a retirement, but only if each conversion is sized to your bracket and done in the right years. Convert too much and you can raise your Medicare premiums and undo the benefit, which is why we map it out year by year.

This is one of the most overlooked risks in retirement. When the first spouse dies, the household usually loses the smaller of the two Social Security checks, and a pension may drop or stop depending on the payout option that was chosen years earlier. At the same time the survivor often moves into a higher tax bracket as a single filer. We plan for that day on purpose, so the income that keeps coming is enough and your spouse is not forced into hard decisions at the worst possible time.

Three differences. First, we are independent: no proprietary products, no captive insurance carriers, no broker-dealer affiliations, no quotas. Second, our only revenue from investment management is the fee you pay us, so our incentive points at your result. Third, rather than managing a portfolio in isolation, we use The Vantage Formula to coordinate every dimension of your financial life: investments, taxes, insurance, and estate.

Applied Wealth Management is fee-based. For investment management and planning, you pay a transparent, agreed-upon fee, with no commissions and no proprietary products on the investment side, so our only incentive is your result. Where we coordinate insurance, we act as a carrier-independent broker and may earn a commission from the carrier; we disclose that plainly and recommend coverage only where it closes a real gap. Every cost is laid out in plain English before you decide anything.

Families, business owners, professionals, and athletes facing genuine complexity. Our typical clients are approaching or in retirement, planning a business succession or sale, managing significant equity compensation, or navigating a short earning window against a long financial timeline. Headquartered in Bakersfield, California, we serve clients nationwide.

The hardest part is starting the conversation. We’ll take it from there.

Tell us where you are and what’s worrying you. We’ll ask questions, listen, and tell you honestly whether we can help.

  • Legally bound to act in your interest
  • Fee-based planning with transparent, plain-English costs
  • Investments, tax, retirement, and estate coordinated under one roof
  • A 45-minute first conversation, with no obligation

Prefer to speak directly? Skip the form and call us. No gatekeepers.

Call or Text (661) 487-1020
I’m interested in

No obligation, and no follow-up pressure if it isn’t the right fit.